A useful way to think about it is this: money reduces friction. It makes exchange faster because you don’t need a direct match for every trade. It makes decisions easier because you can express value in common terms. And it makes planning possible because you can hold value for later.
In everyday conversation, people sometimes ask, “What is money?” The short answer is that money is whatever a community widely accepts as payment and uses to measure value. The deeper answer is that money works because people coordinate around it.
The medium of exchange: why payments feel effortless
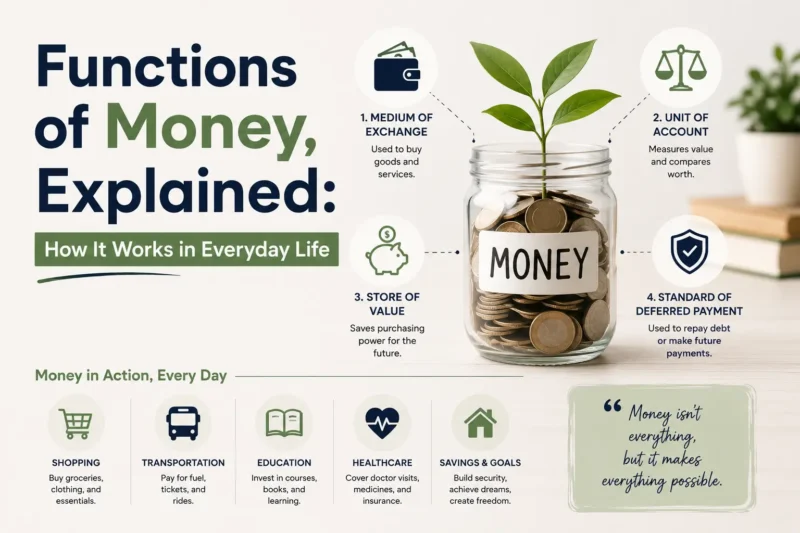
The medium of exchange function is what most people notice first. It means money can be used to buy things because others accept it in return. Instead of negotiating a barter deal—“I’ll give you my service if you give me your product”—you use money to bridge the gap.
Here’s a common example: you buy groceries with cash or a card. The seller may not need exactly what you do for a living, and you may not want what they produce outside of the store. Yet the transaction works because money is an agreed-upon go-between.
This function also explains why payment systems matter. If payments are slow, unreliable, or expensive, the medium-of-exchange role weakens. You’ll see it in real life when cards fail, transfers take days, or fees make small purchases feel annoying. Even if “money” exists, the system around it determines how smoothly it functions.
The unit of account: how prices become a common language
The unit of account function is the reason you can compare options without recalculating everything from scratch. Prices are the visible result. When you see “$12.99,” you’re using a shared measuring stick for value.
This is more than convenience. It’s also how planning works. Budgets, income statements, rent agreements, and subscription costs all rely on a consistent unit of account. Without it, every comparison would require complex negotiation or estimation.
Consider choosing between two services: one costs $40 per month and another costs $60 per month but includes extra features. Because both are expressed in the same unit of account, you can compare them quickly. If costs weren’t standardized, you’d spend far more time trying to translate value into something comparable.
In economics discussions, this is often described as “what is money in economics” at a systems level: money provides a common unit for measuring value. That’s why the unit-of-account function is central to markets.
The store of value: why saving can be both smart and tricky
The store of value function means money can hold purchasing power over time. If you save today, you want that money to still be useful later—at least for your intended timeframe.
In theory, money is a straightforward store of value. In practice, it depends on stability. Inflation can reduce purchasing power, meaning the money you saved might buy less in the future. That doesn’t mean money can’t store value—it means the “quality” of the store of value changes.
Trust also matters. If people lose confidence in a currency or in the institutions that support it, they may prefer alternatives. This can show up as rapid shifts in what people accept for payment or as people rushing to spend money before it loses value.
So when you hear “store of value,” it helps to ask: store value relative to what, and over what time? A short-term emergency fund may behave differently than a long-term goal like retirement. Your best strategy depends on your timeline and the economic environment.
How the three functions work together in everyday decisions
The functions of money don’t operate in isolation. They stack, often within minutes.
When you pay at a store, you’re using money as a medium of exchange. When you decide which product to buy, you’re relying on the unit of account to compare price and value. When you set aside money for later—whether for repairs, a vacation, or a future purchase—you’re leaning on the store-of-value function.
Even decisions that feel “personal” have an economic structure. For example, if you delay a purchase because you want to save, you’re effectively saying: “I trust money enough to hold value until later.” If you choose a cheaper option because you’re worried about future costs, you’re using the unit of account to manage risk.
Once you recognize this, you can make choices more intentionally. You can ask which function you’re depending on in the moment and whether that function is strong or weak for your situation.
Common confusion: definitions vs. functions
People often search for a “15 definition of money” or a “short definition of money,” and it can feel like there should be one perfect statement. But definitions tend to describe what money is, while functions explain what money does.
A short definition might say money is a medium for exchange. That’s true, but it’s incomplete. A more complete view includes the unit of account and store of value. Those extra roles explain why money affects not only buying, but also pricing, saving, and long-term planning.
This is also why “types of money in economics” can be confusing. Different forms of money—cash, bank balances, and other widely accepted instruments—still aim to perform the same core functions. Some forms may be better at certain functions than others depending on convenience, stability, and access.
If you’re trying to explain money to someone else, try this approach: define it briefly, then connect it to the three functions. That makes the concept easier to remember and easier to apply.
When money’s functions weaken, what changes first
Money’s functions are powerful, but they can weaken. Understanding the warning signs helps you avoid making decisions based on assumptions that no longer hold.
If inflation is rising, prices may change faster than your plans. The unit of account still exists, but it becomes less reliable for long-term comparisons. You may notice this in the way people shorten planning horizons, update budgets more frequently, or avoid long contracts.
If payment systems become unreliable, the medium of exchange becomes less “frictionless.” You might see more cash use, more failed transactions, or higher fees that make smaller purchases feel less convenient.
If trust declines, the store-of-value function can deteriorate. People may stop holding money in the same way and look for alternatives. Even without panic, you may see a shift toward assets or payment methods perceived as more stable.
These changes don’t always happen dramatically. Often they appear as everyday annoyances: price surprises, delayed transfers, or budgeting that requires constant adjustment. The key is to recognize which function is being affected so you can adapt.
A practical way to apply this to budgeting and business
Once you have the model, you can use it as a decision tool.
For budgeting, the unit-of-account function is your friend. Use consistent categories and a consistent currency so you can compare spending over time. When costs shift, you’ll spot patterns faster. You can also reduce confusion by separating “fixed costs” (which rely on stable unit-of-account pricing) from “variable costs” (which may move with inflation or demand).
For saving, focus on the store-of-value function relative to your timeframe. A goal in three months needs a different approach than a goal in five years. The point isn’t to chase complexity—it’s to match your choice to how much purchasing power you need to preserve.
For business, medium-of-exchange reliability affects customer experience. If customers face friction at checkout, sales and retention suffer. Unit-of-account clarity matters for pricing strategy: customers compare offers using the shared price language. Store-of-value considerations can influence how businesses structure contracts, manage receivables, and plan inventory.
The functions of money become clearer when you connect them to the decisions you already make. That’s how theory turns into a practical skill.
Where this guide fits in your learning
If you’re also learning “what is money in economics,” this page gives you the framework. Next, you may want to compare how different forms of money perform in markets and daily life. That helps you move from “money exists” to “money works in specific ways,” including the trade-offs behind different payment methods and savings approaches.
You don’t need perfect certainty to benefit from this model. You just need a consistent way to think: money helps exchange, money helps compare, and money helps plan. When those functions are strong, life feels smoother. When they weaken, you’ll know what to adjust.