A stronger approach is to aim for “good enough” clarity. Track in a way you can maintain. Use categories you can recognize quickly. Then review with one question: “What should I do differently next week?” That mindset turns money into a system you can steer.
How to improve money habits without feeling punished
Start with compassion and boundaries. Money habits are usually the result of patterns—stress spending, convenience purchases, or spending that fills an emotional need. If you punish yourself after a bad week, you may learn guilt, not behavior change.
Instead, treat each week as data. Ask what drove the spending: Was it a busy schedule, social pressure, or an unclear plan? Then choose one lever to adjust. For example, if delivery is your leak, you can set a limit, swap in a planned meal routine, or create a “replacement” activity for the same time of day.
The goal is not perfection. The goal is a plan you can follow on your busiest day.
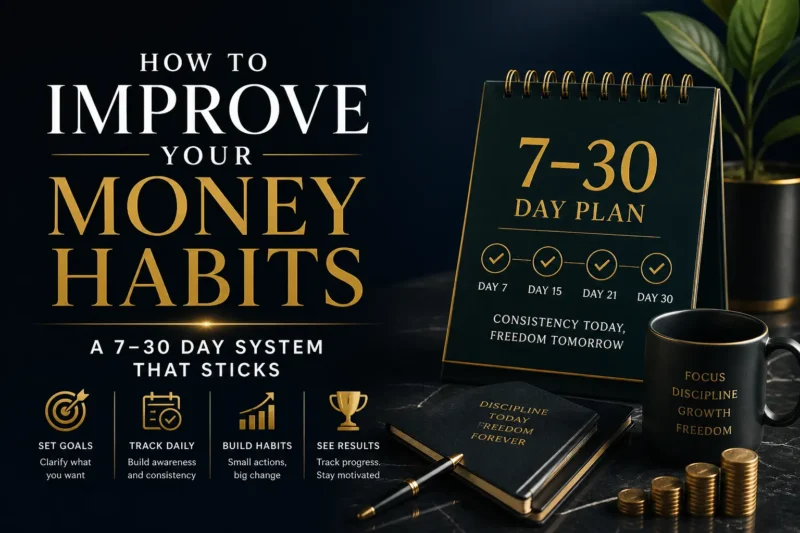
The 7-day clarity sprint: track like a realist
For the first week, you’re not building a budget—you’re building awareness. Choose one tracking method and commit for seven days. If you use a money app, keep it simple: categorize purchases into broad groups. If you prefer manual tracking, use notes and totals by category.
When you’re done, don’t just scan numbers. Look for patterns you can act on:
- Recurring spending: subscriptions, memberships, “set-and-forget” charges.
- Convenience spending: delivery, last-minute purchases, fees.
- Decision categories: groceries, fun, dining out—places where choices happen daily.
A useful trick is to write down one sentence: “I overspend most when ________.” That sentence becomes your next habit target.
Where your money mindset shows up in daily choices
Money mindset isn’t just motivation quotes—it shows up in what you do when you’re tired, busy, or tempted. Maybe you feel like budgeting is restrictive, or you believe saving means you’ll miss out. Or maybe you grew up with chaos around money, so your nervous system treats bills like a threat.
To improve your money habits, you need a mindset that supports action. Replace “I’m bad with money” with “I’m learning my patterns.” Replace “I have to be perfect” with “I only need to be consistent.”
You can also build a small “confidence ritual.” For example, every payday you check your savings transfer and confirm it happened. That tiny action trains your brain that progress is real.
How to build a budget that matches your life
A budget should feel like a map, not a cage. Use a structure you can maintain. If you’re paid regularly, you can assign categories per paycheck. If your income varies, budget using averages and include a buffer for irregular weeks.
Try this practical rule: if you can’t explain your budget in two minutes, it’s too complicated for the way you’ll actually live.
A simple category approach works well for most people:
Needs: housing, utilities, minimum debt payments, groceries basics.
Wants: dining out, entertainment, subscriptions you enjoy.
Savings: emergency buffer, short-term goals, and any debt payoff above minimums.
Then add one boundary: choose one category you will not exceed without a trade. For example, “If I spend extra on dining out, I reduce groceries or fun later.” This keeps your plan flexible without giving up control.
The “money picture” that guides better decisions
When people say “see your money,” they often mean spreadsheets. But a money picture can also be emotional and behavioral: what you notice, what you avoid, and what you automatically do. For some readers, real money pictures—like screenshots of balances or a quick weekly breakdown—can help you stay grounded.
If you don’t want to look at numbers daily, create a weekly snapshot. Once a week, check your balances and confirm your savings transfer. Then decide one small adjustment. This approach supports decision-making without turning your finances into constant stress.
If you’re tempted to chase “money 100” ideas—big, dramatic changes—remember: habits don’t change in one day. They change when your environment and routines make the better choice easier.
A 30-day plan for building momentum
Once you’ve tracked for a week and set your categories, the next phase is repetition. Your job is to keep the system running long enough for it to feel normal.
Here’s what “momentum” looks like in practice:
You review spending weekly for 10–20 minutes.
You adjust one category instead of rewriting the whole plan.
You keep your savings habit automatic.
You use a trigger to reduce decision fatigue.
If you miss a day or a week, don’t restart from scratch. Resume tracking and focus on the next decision. The fastest way to lose progress is to treat a slip as failure.
Common mistakes that keep money habits stuck
Many people stall because they aim for the wrong kind of change. Here are the most common pitfalls and what to do instead.
First, setting goals that are too vague. “Save more” is hard to measure. A better goal is a weekly amount or a clear category limit.
Second, tracking everything perfectly. When tracking becomes a job, people quit. Instead, track consistently and simplify categories. You’re looking for patterns, not auditing.
Third, building a budget that ignores reality. If your plan assumes you’ll never spend on takeout, you’ll likely break it and then abandon the budget. Choose one category to flex and one to protect.
Fourth, skipping the emergency buffer. Without even a small buffer, unexpected expenses trigger credit-card use, which can undo progress. Start with a realistic starter amount.
Finally, relying on willpower. Willpower is unreliable. Habit triggers and automation beat motivation. Set up a transfer on payday, and use a rule for impulse moments.
Advanced tips for stronger results
If you want a bigger shift, focus on reducing friction and improving feedback.
One advanced strategy is to “pre-commit” to trade-offs. Before you spend, decide what you’ll reduce later. For example, if you plan a social event, decide which category will fund it. This prevents the “I’ll figure it out later” spiral.
Another strategy is to protect your high-emotion spending windows. Many people overspend when they’re hungry, stressed, or scrolling late at night. Create a simple replacement plan: a snack you keep at home, a 20-minute walk, or a saved shopping list you review only during daylight hours.
You can also use a two-level system: a baseline plan plus a flexible override. Baseline is your normal budget. Override is when life happens—then you adjust one category temporarily instead of breaking everything.
If you’re trying to earn money free—through side gigs, reselling, tutoring, or freelancing—pair that with a habit plan. Extra income helps, but only if you direct it somewhere consistent (like savings or debt payoff) and don’t automatically raise spending to match.
And if you’ve been using a money app or experimenting with “money pic” style reminders, keep what works. The best tool is the one you’ll actually open and use weekly.
When to get more support
This guide is built for self-directed change. But if you’re dealing with serious debt stress, panic around bills, or spending that feels out of control, consider getting support from a qualified professional. A credit counselor, a financial coach with ethical standards, or a therapist for compulsive spending patterns can help you build a safer plan. You deserve help that respects your situation rather than shaming you.
Final thought
Improving your money habits is less about finding the perfect budget and more about building a repeatable system you can follow when life is messy. Start with a short clarity sprint, then set a budget that fits your real spending categories. Add one measurable goal, automate a starter emergency buffer, and review weekly for small adjustments. If you stumble, resume—not restart.
Give yourself time. In 7 days, you’ll understand your patterns. In 30 days, you’ll have a plan that feels familiar. That’s how change sticks.